All Categories
Featured


Choosing Whole Life versus Term Plans
It's also a good choice if you think you'll need to change your premium and death advantage. However you may not need a life insurance policy after you've paid off your debts and saved for your huge monetary objectives, like retirement and your kid's college education. In these situations, a term life insurance coverage policy with a different retirement fund and other savings vehicles might offer what you require, and at a lower price. An independent agent can stroll you through your choices to discover the best coverage quantity for the finest cost with a trusted insurance provider. Once you have a few quotes, you ought to: Compare protection limitations, approximated month-to-month payments and administrative or management fees that include each policy. Select a policy and an insurance company. The company might ask you to go through a phone interview or medical examination. As soon as approved, start paying premiums regularly. Indexed universal life insurance uses irreversible protection with a death benefit and a money value that grows based on underlying financial investments. You can either assign the money worth portion in a repaired account, an indexed account or both.
Instead, the insurance coverage business utilizes the index as a standard to figure out how much interest to credit to the cash worth part of your policy. If the index has a bad year, your credited interest may be lower(in some cases even 0%), depending on your policy's terms. If your policy credits the.
full 10Complete, your cash value money earn might $5,000 in interest before fees and policy charges.
Even though the index increased by 15 %, your policy would just be credited 10 % before charges and other policy charges. If your policy has an 80 %participation rate and the index increases 10%, you would get 8%interest (80%of the index's gain), assuming no cap restricts the return. The majority of indexed universal life policies let you choose in between two types of death advantages: Your beneficiaries receive a fixed death advantage throughout the life of the policy.
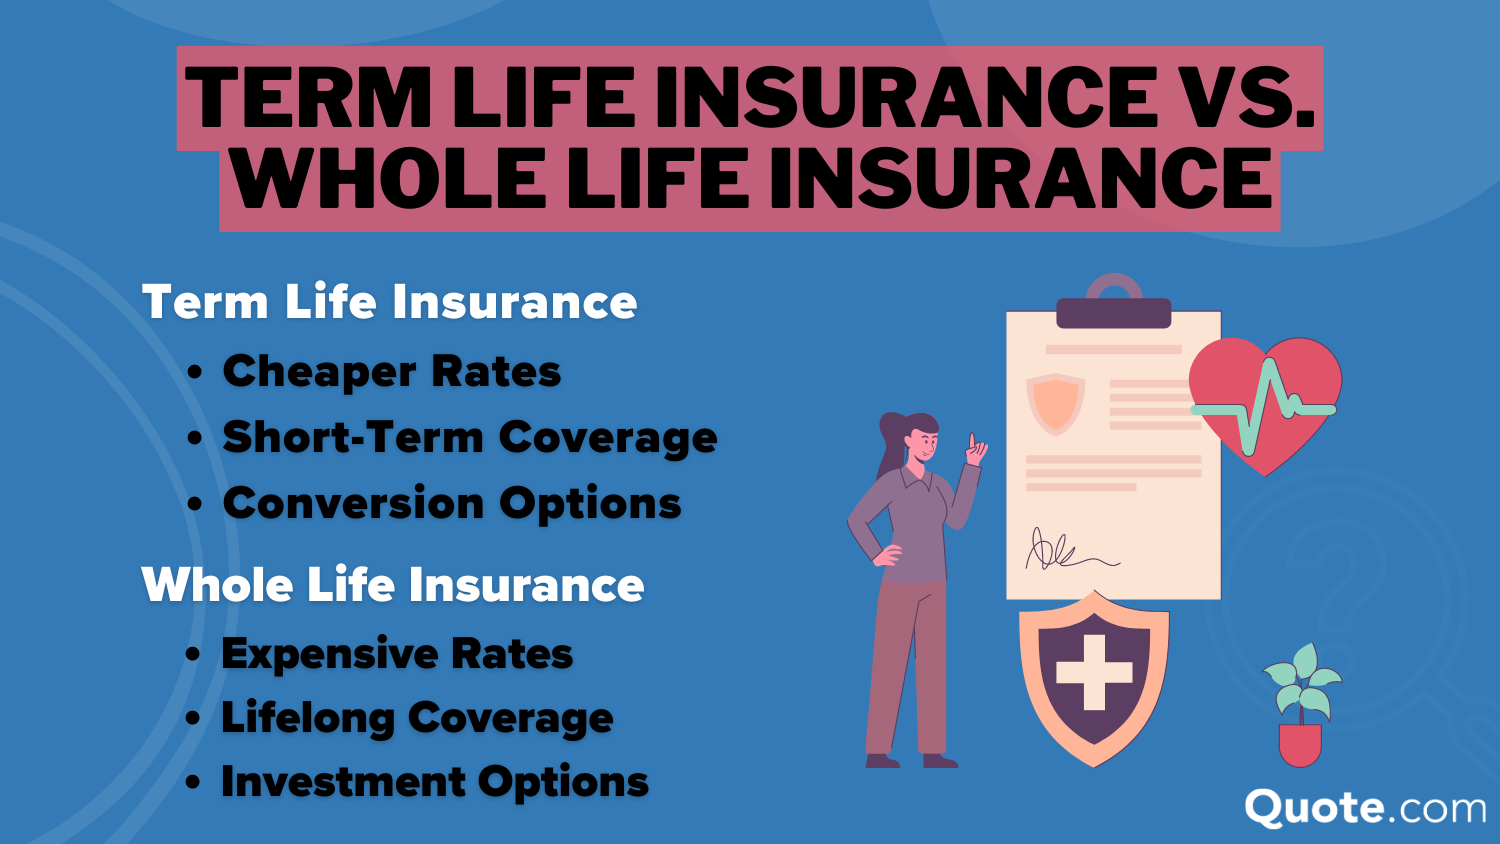
Comparing Term vs Whole Life Policies
That versatility can be huge if your income changes from year to year, or you go through a big life event (such as divorce or short-lived work leave) and still want to keep your policy in force. It likewise means you'll need to pay closer attention to your policy over time.
Medicare in EscondidoThis table highlights the greatest differences: Both entire life insurance and indexed universal life supply you with irreversible coverage that develops cash value, however how that money value grows is rather different. Whole life insurance normally has guaranteed growth at a fixed rate, while IUL has the capacity for higher returns since its money worth is tied to a market index.
Term life insurance is normally the most budget friendly and easiest kind of life insurance to get. It doesn't develop money value, however you get a guaranteed survivor benefit for a set period of time, often at a portion of the expense of an IUL policy. You can consider a variable universal life insurance policy as one step above an IUL policy in terms of risk and benefit.
Medicare in EscondidoThis implies you'll have higher development capacity but likewise the possibility of investment losses. Like any monetary item, indexed universal life insurance coverage has benefits and compromises. If your main objective is just replacing your income for your family, a term life insurance coverage policy is generally easier and far more economical.
Typical expenses might include:, which normally increases as you age for managing the policy deducted from your payments if you include functions like long-lasting care or chronic illness advantages if you cancel the policy during its early years Before you buy an indexed universal life policy, the insurance company will normally supply an illustration showing how your policy could perform over time.

Latest Posts
PPO vs HMO Health Insurance Plans

Securing the Best Individual Medical Insurance Rates
Securing the Best Individual Health Insurance Quotes