All Categories
Featured
Affordable Life Insurance for Veterans
Table of Contents
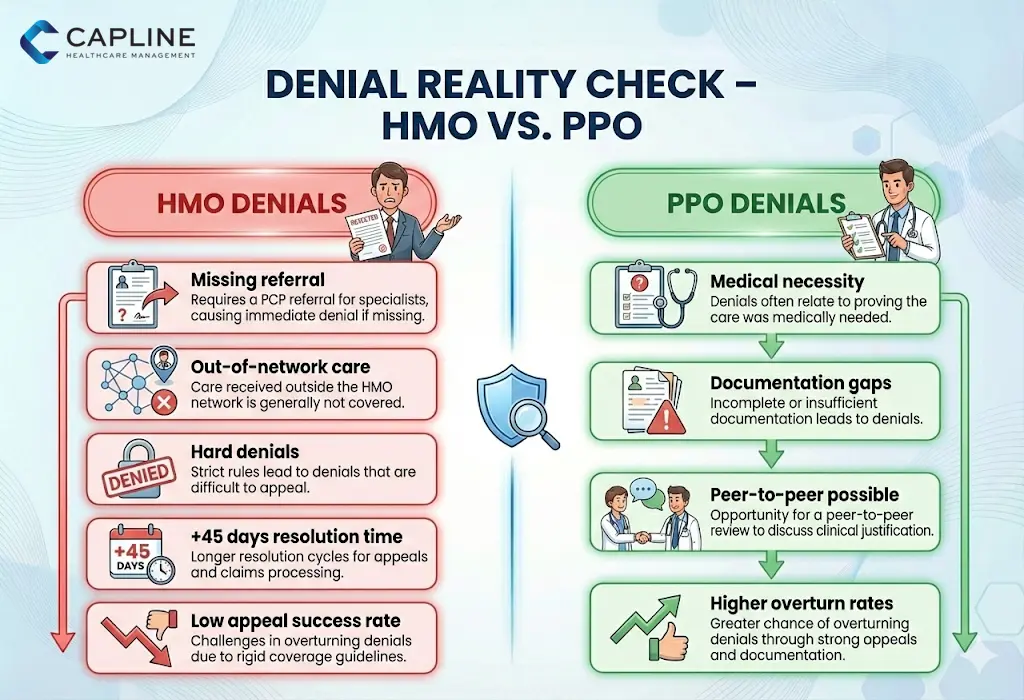
An HMO insurance coverage plan is typically regarded as being more affordable due to its lower monthly premiums and hassle-free due to its requirement that patients must have a medical care doctor to manage their care. A PPO insurance strategy is understood for its versatility as it enables clients to manage their own care and look for numerous providers/specialists without needing a referral.
Similar to general insurance coverage strategies, the two main Medicare Advantage plans are HMO and PPO.While HMO and PPO insurance plans continue to be the most common choice for patients to pick from, there are a variety of other insurance coverage alternatives. HMO and PPO insurance coverage strategies are the 2 most common healthcare insurance strategies in the United States.
While these insurance strategies are various, they are similar in the sense that they provide a client with a network of doctors, medical facilities, and other health care providers that aid members with their health-care journey. "HMO" acts as an acronym for "Health care Organization," while "PPO" works as an acronym for "Preferred Supplier Company." An HMO insurance plan is centered around a variety of health centers and healthcare suppliers (referred to as an "HMO network") that have concurred to treat clients within the network's insurance strategy. A referral is necessary for a patient to see other specialists that are in-network or out-of-network, and often, receiving out-of-network care just happens in emergency scenarios. This strategy offers lower monthly premiums for its customers, making it an affordable insurance coverage option. Low month-to-month premiums. Not as numerous claims to file due to in-network care.
Often, lower expenses for prescriptions. A patient can only see service providers within the strategy's network unless they have a recommendation for an outdoors specialist, or it's an emergency scenario.
Comparing HMO Network Access versus Monthly Costs
This strategy also lets the patient collaborate their care and manage which suppliers they want to see, versus having a primary care medical professional. The client has more flexibility with which service providers they pick to see, whether they're within the strategy's network or out-of-network. Most times, there is no requirement for a referral if a patient cares to see an out-of-network expert.
The client is accountable for managing their healthcare, vice a medical care doctor being in charge. A 'supplier network' refers to the list of doctors, professionals, hospitals, and so on that an insurance coverage agency contracts to provide medical services to its strategy members. Suppliers that are 'in-network' refer to the health care workers and healthcare facilities that are listed in the strategy.
Insurance in Rancho Cucamonga CAThe expenses associated with an HMO plan consist of deductibles, which is the quantity a client must pay before insurance contributions, and month-to-month premiums, which is the amount taken out of a client's income. Typically, the monthly premiums taken out with an HMO plan are lower than a PPO strategy's premiums.
Yearly, this resulted in a $6,869 coverage on people and $19,445 coverage on families, revealing a lower monthly premium in comparison to a PPO strategy type. Deductibles, month-to-month premiums, and copays are costs commonly associated with a PPO plan. The majority of times, the month-to-month premiums are taken out with a PPO strategy that is more expensive than an HMO plan's premiums.
Securing Final Expense Protection for Families
According to the Kaiser Family Structure 2018 Health Benefits Survey, all companies utilizing a PPO insurance coverage plan paid $592 as the month-to-month premium on an individual and $1,694 as the monthly premium on a family. Yearly, this led to a $7,149 protection on people and $20,324 coverage on households, revealing a greater month-to-month premium in comparison to an HMO strategy type.
When attempting to decide which plan is best, there are lots of elements to think about, with some of the most essential being versatility, expense effectiveness, and coordination of care. If it's versatility that is essential, then a PPO insurance coverage plan might be a much better suitable for they enable a client to have more control over which companies they see and when, regardless of a referral.

Another advantage to an HMO plan is that it needs a client to have a medical care physician that collaborates their look after them. This means that with a PPO insurance coverage plan, the patient will have to handle their own care and manage which providers/specialists they need to visit. In the end, one plan is not considered better than the other.
Health insurance strategies do not cover dental insurance coverage. To find out more on obtaining an oral plan, such as a dental HMO strategy, 'DHMO strategy,' or a dental PPO strategy, 'DPPO plan,' visit this resource. When an American (who has actually been paying Medicare taxes for a minimum of 10 years) turns 65, they receive the health insurance coverage strategy understood as Medicare.

Latest Posts

Securing the Best Individual Health Insurance Quotes

Maximizing Long-Term Security Through Life Insurance
Exploring Indexed Universal Life Benefits for Retirement